Tuesday, September 1, 2015

IKEA Hack - Kivik Sofa (New Legs)


After E and I bought our new home and before we moved into it, I spent literally weeks trying to decide what to do with the living room.  I wish I was kidding but it was almost a full time job pouring over blogs and Houzz to try and determine the answer to my many questions like:

-          What colour sofa should I get for white walls and light flooring

-          Is leather better than fabric?

-          What size of sofa should we get?

-          Should we do one long sofa and two arm chairs or one loveseat and two arm chairs or two matching armchairs?

This is just a sampling of the questions that really kept me up at night.  Hilariously, I had never taken an interest in house décor before this point in time, unless you could all the posters I bought at the college poster sales (back when buying posters off the internet was not a thing – I know, I am dating myself).

Anyhow, after much agony and deliberation I finally decided on two matching loveseats… but did you know how many sizes of loveseats there are?

Some are big.  Some are small.  I decided that as we were on a budget, we should go with a fabric sofa.

Enter my work colleague who rescued precious dogs from the Turks and Caicos and was looking for an owner.  Introduction – my allergies.  I had dogs growing up and knew first hand the importance of leather sofas and hardwood floors to my survival.  So, the beautiful fabric sofa from a brand name store I wanted?  No longer an option.

What is a girl to do?  I was back to square one spending hours researching my options.  Eventually I settled on (I am sure you have guessed it as I now realize the title gave it away) IKEA leather.  I then had to agonize over what type of sofas to get from IKEA.  Fortunately there is no shortage of reviews and opinions and DIY on IKEA sofas out there, so I recommend visiting HERE and HERE for more information.

We decided to go with the Kivik, after I determined that the measurements of the Kivik were absolutely mid way between a normal love seat and a sofa, which was exactly what we needed for our strange narrow space.  Plus, you could sit on the wide arm chairs and E of course did the “lay down and relax test” and he was happy with it, even though it was certainly smaller length wise than he would consider ideal. 

Hilariously, despite the fact you are getting an entire foot less of sofa, you only save 20$ on the loveseat over the sofa.  I mean, part of that made sense to me, but the part of me that wished we had a slightly wider house was pretty upset about the whole thing.

Now, the one thing I had found during my IKEA research was an IKEA hack – replacing your original IKEA legs (blocks of plastic sadness) with fancy new legs.  After a lot of research, I ended up caving and going with Uncle Bob’s Workshop, in the hopes that his design would ensure the stability of these precious $979 couches.  You can find the link HERE, but as a warning – he is usually several months behind on his orders due to his popularity and the fact Uncle Bob is really the only employee from what I can tell.
Once they arrived, months later, I re-agonized over the colour.  Did it make sense with our light flooring?  Would it look strange? In the end, my research (see a pattern here with me?) indicated the resounding conclusion to this concern is “Who cares it all looks like wood anyways and wood almost always matches” so I decided to try to put them on.

The process is smooth enough, although I highly recommend reading Uncle Bob’s instructions before attempting to install on your own.  That being said, clearly I did not do that, and I still got them on by myself.  One important thing to note is that the Kivik apparently has two sizes of adapters and I thought I had to buy the 2cm size – in the end I was the 1.8cm size.  What is a girl to do?  I had waited for months for the legs.  So, I got out the sandpaper and I and watched Netflix reruns while sanding down to the appropriate size.  How can one be both patient and impatient at the same time? I have done it.

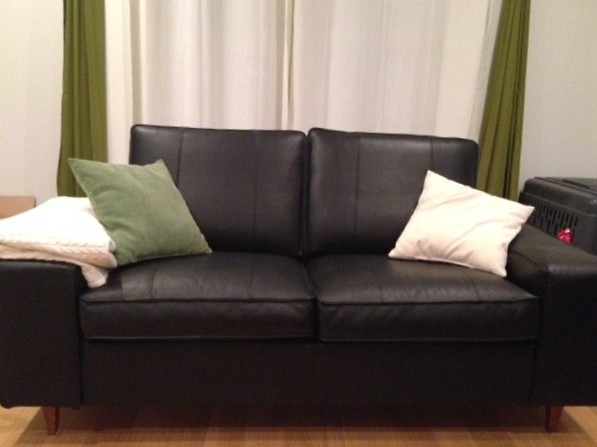
The result? Not what I was expecting, sadly.  The Kivik sofa is a bit clunky.  After I put the legs on, I wished I had considered buying a wider, more blocky leg to match.  I could likely have returned them to Uncle Bob to get a different style, but I didn’t bother because I live in Canada and it costs approximately a million dollars to return things to America unless you conveniently live within 50 kilometres of the US border (I do not).  Plus it is possible that buying a thicker leg would have just made it look more clunky.

Side
Front
(Dog kennel is not a recommended design element on any blog)

What I will say is that the IKEA hack made the couches go from looking pretty low on the ground and IKEA like to a much more reasonable height and looking like I might have spent money on them.
I won’t be taking the legs off and as indicated on all the advice blogs, the natural light coming in from under the couches for this narrow living room truly make all the difference.  Blocking out that light in our tall ceiling narrow living room was not a good choice, so I am happy about this change.   The couches feel extremely sturdy and I was pleased with my handywoman efforts.  But my number one recommendation would be to actually measure the size leg you are considering buying on a piece of paper, cut it out, and putting it up against the sofa to see if the size makes sense.

Oh, and in terms of the leather choice- so great.  I was surprised that the leather felt nice and soft after a very short amount of time and the couch has held up great to the dog, who has taken to sleeping on it. 
 
-C

Monday, August 31, 2015

Soup Stock

I only started to hate buying chicken stock when I no longer had a car.  Hauling even 4 Litres of chicken or vegetable stock was a chore, and it meant I couldn't buy milk at the same time.  It also cost $10 for 4 litres of stock, which just seemed bizarre.

At some point, I decided there had to be a better way.  I turned to the internet for advice.

Chicken and vegetable stock, as it turns out, basically makes itself when you are making a chicken soup.  You boil the bones you were going to throw away, along with the parts of the vegetables you weren't going to use.  You toss it in a big pot with salt, a few spices, and boil it.  Then you strain it!

Here is a recipe for you: http://www.simplyrecipes.com/recipes/how_to_make_chicken_stock/

And another: http://www.simplyrecipes.com/recipes/how_to_make_chicken_stock/

This is generally how I do it:

  • 1 roasted chicken carcass (Safeway chicken for $8.99)
  • 1 large yellow onion cut up into chunks (no need to dice)
  • 1 tablespoon of diced garlic (you could also just press your own)
  • Leftover celery and carrot
  • Salt and pepper
  • Thyme (small amount)
Sometimes, I am missing carrots or celery, and I just do it up anyways.  If you aren't using the broth for chicken noodle soup, you can get away with it as the base for other soups.  I bring it to a boil and then let it simmer for a few hours before letting it cool and then straining it all out - by far the messiest part of the task.

Of course, I don't put my chicken stock in adorable little mason jars like the ones linked above.  I either make it into a soup right away, or I freeze it in Tupperware.  There are health benefits to making your own stock, and it definitely is less salty.  I can't imagine going back to the canned stuff and think of all the money you can save!

Here is a picture of the messy work!

Your Tax Return Does Not Belong to You


Isn’t it great?  You finish school and are finally making some money.  You are finally in a position where you make enough money to be taxed.  What a life.  Then you discover that you have all these education credits!  Unused!  You file your taxes at H&R Block like a champ and then greedily wait for that cheque to come in.  What are you going to do?  Take a nice vacation?  After all, you are working hard, you deserve a break!  Buy a new bedroom set? After all, you need to look like an adult at work!  Go to Hold Renfrew? I deserve this treat and I have been really eyeing these new sandals.


No.  None of the above.  THIS MONEY DOES NOT BELONG TO YOU.

“What?” you ask? “How can that be?  I worked hard.  I get the tax return cheque. The government puts no restrictions on what I do with this money, so why should you?  I hate reading this stupid blog.  You are stupid and pretentious and think you are so moral with your savings ways.  Get bent.”

A fair reaction.  I don’t blame you.  But I am telling you, the tax return doesn’t belong to you.  It belongs to the student loan.

How does one come to this conclusion?  It is actually alarmingly straight forward, but because the government likes us to make decisions for ourselves and most student loans are really private bank loans at a decent interest rate, we usually end up spending our tax return on hookers and blow, or whatever the going vice and associated drug is these days.  For the record, my friends seem to prefer Holts and wine, but its really all the same problem.

Do you remember when you took out that student loan?  What did it pay for?

Courses.  Fees.  If you were lucky, rent!

When you filed your tax returns when you were a student (if you did – otherwise, you have a lot of work to do) what did you get from the University/College to help fill in the forms?  A little T2202A that outlined what you had paid in fees that year.  You included that, as well as the credit for the months you were in school for (full time or part time) and you didn’t look at the forms ever again.  Because back then, you didn’t use your credits.

Fast forward to post-graduation when you are receiving a real paycheque.  All of a sudden Troung and H&R Block is telling you that $7,000 is coming your way.  Now for all that money you spent on post-secondary education, SOME of it is coming back to you.  I can’t emphasize this enough.  Even in the best case scenario, you are only using the credits to decrease your total income.  You don’t get the credits back dollar for dollar.  The $20,000 credits will decrease your income, and so those taxes you paid will be returned.  About 40% depending on your tax rate and salary.

So you already used this money.  You used it on COMS 201, LAWS 491, ENGG 345 – its been used.  You took out the loan for it.  Now, you got some credits for spending all that time and money back in the day.  So that money in the tax return isn’t yours.  It belongs to your student loans.  It belong to past, poor you, who if you had the money would have paid for school yourself.

Every time you get a tax return over $50 do this – treat yourself to keeping $100 for something. I am not an animal.  I am not unrealistic.  Its cruel asking for somebody to fork over all that cash when all your friends are stopping at Holts.  But take the $100 and the rest – it should all go to your loans.  The education credits were never yours in the first place.

Business Expenses = Free Points

Some companies make you sign up for a corporate credit card, and all credit card purchases must be made on that credit card.  This post will be entirely useless to you, so feel free to move on and check Facebook again!


Most of you however will work at a company that merely reimburses you for expenses.  You pile up the charges on your credit card, then submit the receipts later.  This is a fantastic thing.

The reason it is so great is because with the right card, you can rack up the points without ever spending a dime of your own money.  It important to do your research on your points card and choose what is right for you.  I am not here to re-invent the wheel, so you should really just check out these sites which compare credit cards for you so that you make sure you get the best deal for what you want, whether it is travel, gift cards, or cash back. 

http://www.moneysense.ca/debt/credit-cards/canadas-best-credit-cards-of-2015/

http://www.greedyrates.ca/blog/best-travel-credit-card-canada-2015/#.VeUr3ZVRHX4

No matter what, we can safely refer to these as "points".

Let's say you don't want to use credit cards - you always spend more than you have.  This will still work.  You get a credit card only for corporate purchases.  Keep it in your office desk drawer until you need it even.

Assuming you have that credit card, you are going to be making money off of doing your job.  For example, I had a Costco MasterCard which gives me cash back (to Costco).  It's 1% for most purchases, 2% for gas, and 3% for restaurants.  Let's say you work at a company that lets you take clients out for lunch, has a decent amount of travel, and also makes you plan (and pay for) the company family barbeque.

Restaurants - $2,400 per year
Gas - $600 per year
Groceries for BBQ - $1,500 per year

So, what's the grand total?
$72 + $12 + $15 = $99

Now, you need to make sure you are going to pay for the annual fee.  I used to have a RBC Rewards Visa card, and I took two university students to Oregon for a competition once.  This was the benefit (other than the great trip!):

Flights (3) return plus insurance - $3,000
Hotels (3 rooms for 2 nights) - $1,200
Meals - $600
Total = $3,800 = 3800 points

What can you get for 3800 points? A 25$ gift card to the Bay, which might be enough to stretch to buy gifts for a friends baby shower if you buy everything on sale.  Or you save up for a year, and have enough to buy presents for a wedding you have next year.  It all helps.


Wednesday, October 31, 2012

The Wealthy Barber Returns

Three things to know about my one and only financial book, The Wealthy Barber Returns:
  1. Apparently, he "returns".  There is an original book out there, written many moons ago.  I didn't read it.
  2. There is no such thing as an actual wealthy barber (he made it up in the first book, presumably choosing the profession of barber to make saving seem attainable and easy)
  3. It has somehow managed to scare me into worrying about saving for my retirement.  I'm 26.
This book is great.  It's the only financial book I've ever read, and it may be the only one I ever read.  It explained the difference between RRSPs, RESPs, TFSAs, the list goes on.

I highly recommend this book.  I highly recommend that you don't run out and buy it, but borrow it from your local Public Library (post to come soon on why libraries rock).  

Trust me, the author won't be mad I suggested this.  I learned these things from him, after all.  The book was a gift from my Nana, so special shout out to her!

Welcome...

I am not really the blogger type- I don't have an interesting hobbies, take many professional looking photos, or follow fashion.  I don't really have a passion for much of anything past my job and socializing. But I realized, watching an episode of "Princess" on Slice that I have a passion for something... finding ways to cut my costs, save my money, and eventually "Pay it all back".

I acquired quite a bit of debt going to school, partly enabled by seemingly endless funds in a Line of Credit (LOC) and generous Provincial and Federal Student Loans.  Combined with an insatiable desire for travel, it was a recipe for disaster, or, at the very least, a lot of debt and interest payments.  I managed to pay off $70,000 in just 27 months. 

I'm hoping that with this blog (if anybody ever reads it) you learn interesting new ways to save money beyond the "don't buy a cup of coffee" advice you usually hear.


- C